Lecture 11

Continuous Distributions (Part 2)


Grace Tompkins

Last modified — 23 Oct 2026

Learning Outcomes

By the end of this lecture, students are anticipated to be able to:

  • Identify various continuous families or RV
  • Use known distributions to solve for word problems

1 Continuous families

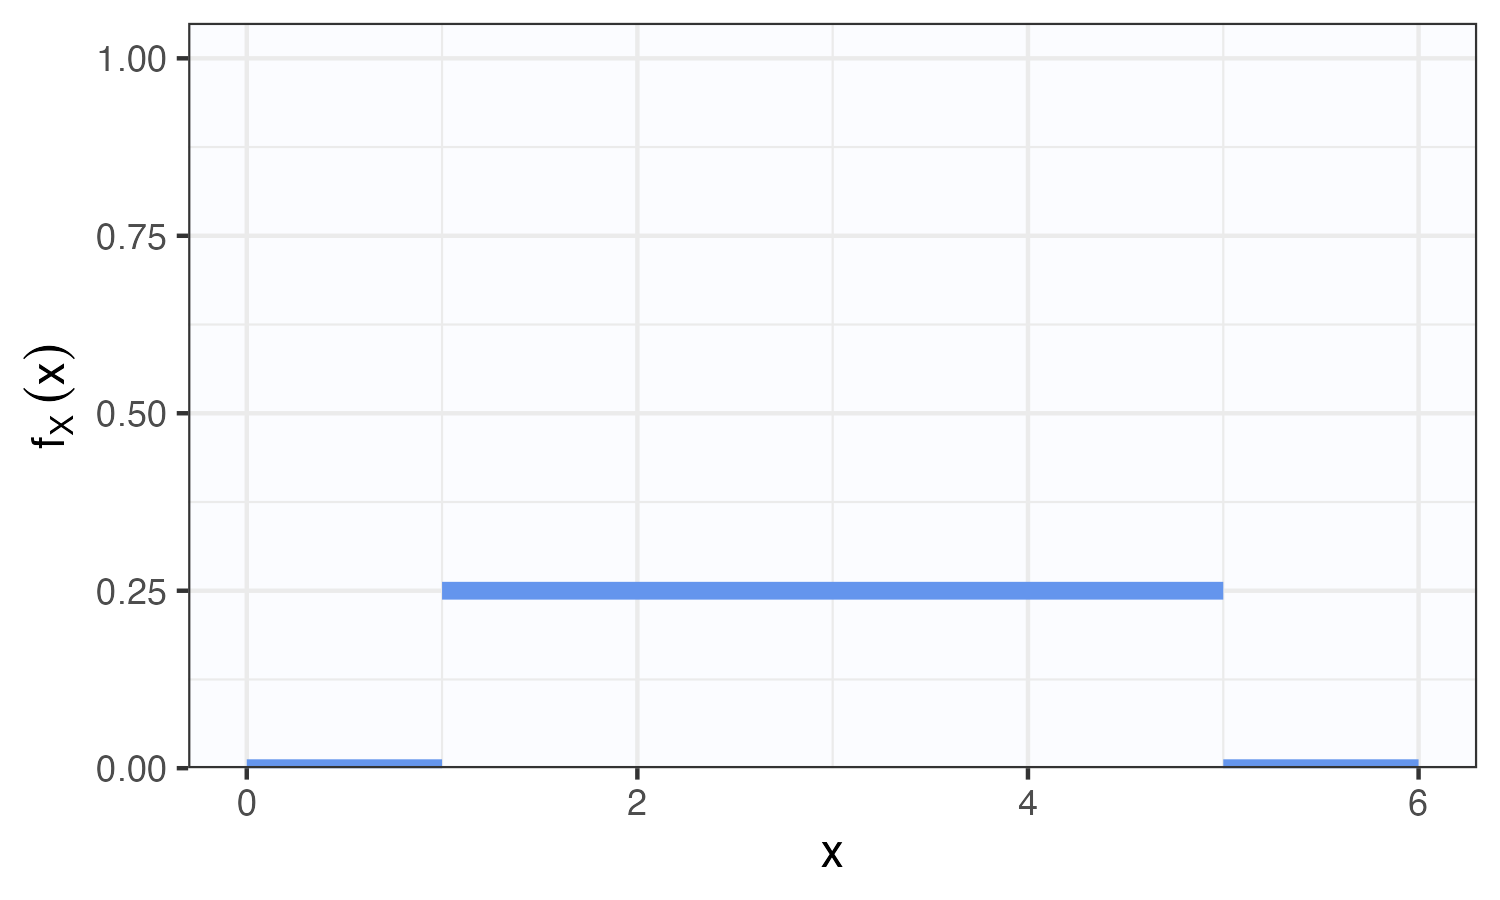
(Continuous) Uniform

Let \(L < R \in {\mathbb{R}}\). A RV \(X\) with PDF \[f_X(x; L, R) = \frac{1}{R-L}I_{[L,R]}(x),\] is said to have the \({\mathrm{Unif}}(L,R)\) distribution.

\[ \begin{aligned} \mathbb{P}(a< X < b) &= \frac{1}{R-L}\int_a^b I_{[L,R]}(x) \\ &= \frac{b-a}{R-L}, \end{aligned} \] whenever \(L\leq a<b\leq R\).
Continuous Uniform Median

For continuous random variables, the median is the number \(m\) such that \[\mathbb{P}(X<m) = \mathbb{P}(X>m) = 1/2.\]

Let \(X\sim{\mathrm{Unif}}(L, R)\). What is the median of \(X\)?

Continuous Uniform Median

Exponential Distribution

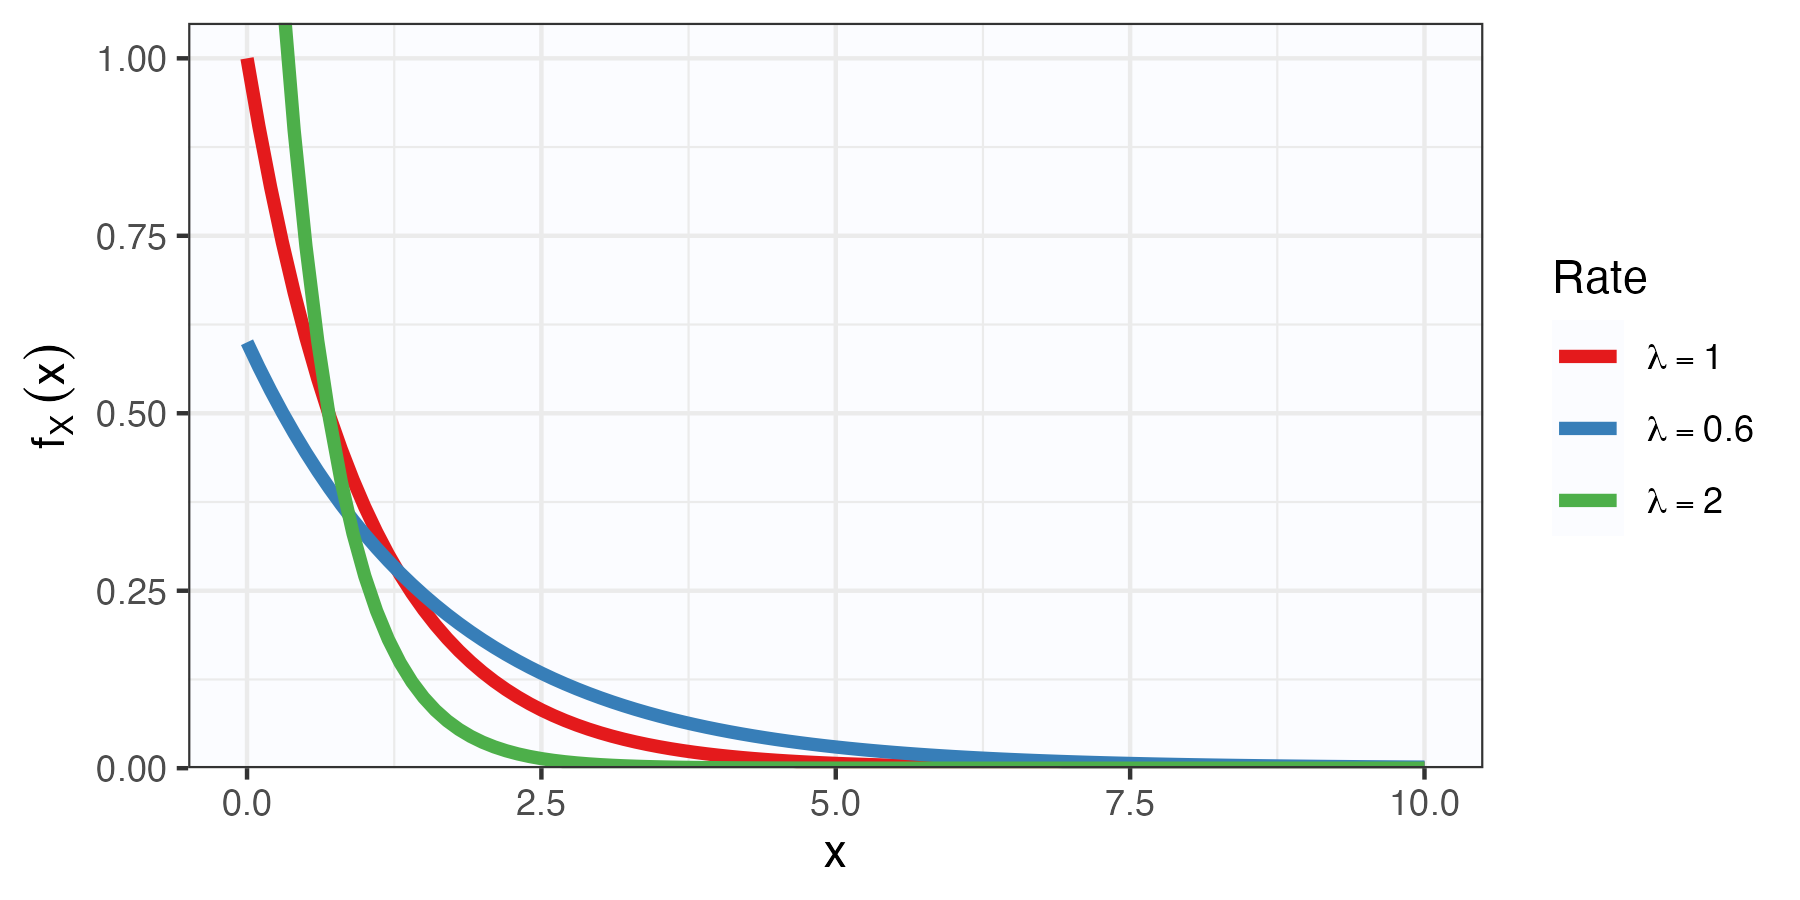
Let \(\lambda>0\). A RV \(X\) with PDF \[f_X(x; \lambda) = \lambda e^{-\lambda x}I_{[0,\infty)}(x),\] is said to have the \({\mathrm{Exp}}(\lambda)\) distribution with rate \(\lambda\).
Exponential Distribution

  • The exponential distribution is good for modelling the number of time between independent, random events (i.e., wait or inter-arrival times).

  • It is related to the Poisson model, which models the number of events within a given interval!

Exponential Distribution

\[f_X(x; \lambda) = \lambda e^{-\lambda x}I_{[0,\infty)}(x)\]

Let \(Y \sim {\mathrm{Exp}}(2)\). Find \(\mathbb{P}(Y > y)\) for \(y>0\).

Exponential Distribution

Exponential Distribution

A small coffee shop receives customers independently at an average rate of 12 per hour. Let \(T\) be the waiting time (in minutes) between consecutive customer arrivals.

  1. What distribution does \(T\) follow, and what is its rate parameter \(\lambda\)?

  2. What is the probability that the next customer arrives within 3 minutes?

Exponential Distribution

Gamma Distribution

Recall the gamma function:

\[ \Gamma(\alpha) = \int_0^\infty t^{\alpha-1}\exp(-t)dt, \text{. where } \alpha > 0 \]

Useful results:

  • \(\Gamma(\alpha + 1) = \alpha\Gamma(\alpha)\)

  • If \(\alpha\) is an integer, this integral simplifies to \(\Gamma(n) = (n-1)!\)

  • \(\Gamma(1/2) = \sqrt(\pi)\)

Gamma Distribution

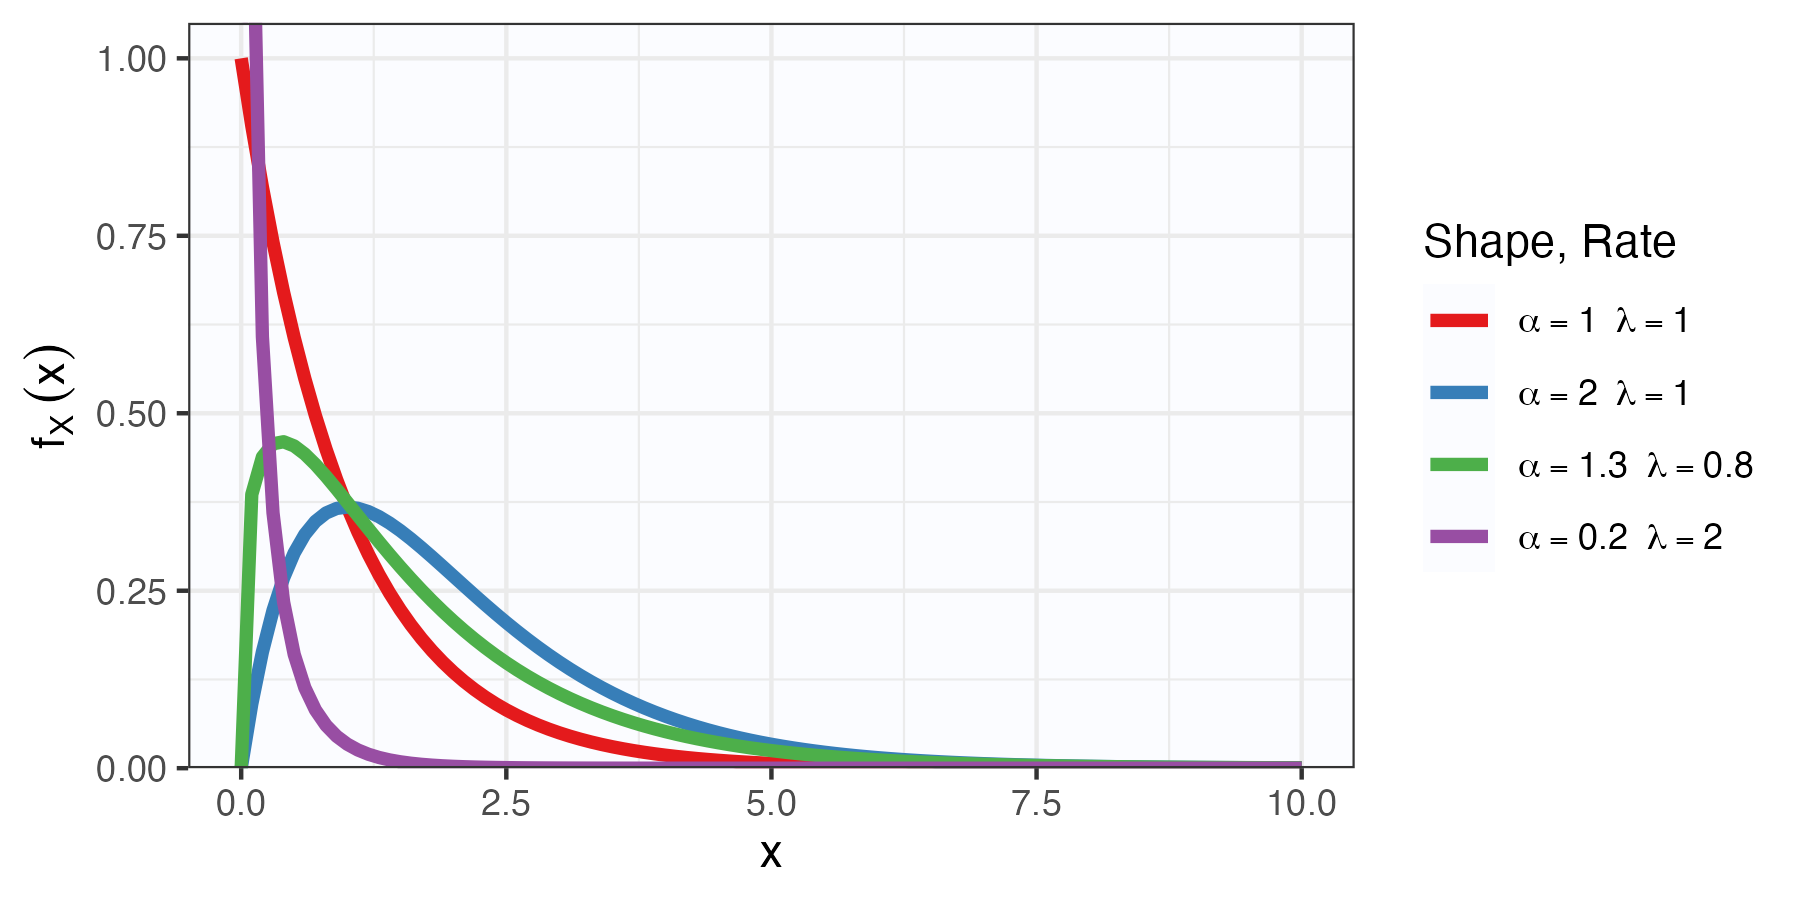
Let \(\alpha, \lambda>0\). A RV \(Z\) with pdf \[f_Z(z; \alpha, \lambda) = \frac{\lambda^\alpha}{\Gamma(\alpha)} z^{\alpha-1}e^{-\lambda z}I_{[0,\infty)}(z),\] is said to have the \({\mathrm{Gam}}(\alpha,\lambda)\) distribution with shape \(\alpha\) and rate \(\lambda\).

Note: \(Z\sim{\mathrm{Gam}}(1,\lambda) \Rightarrow Z\sim{\mathrm{Exp}}(\lambda)\).
Gamma Distribution

The time to process an insurance claim follows \({\mathrm{Gam}}(\alpha = 2, \lambda = 1/3)\). What is the probability that the claim takes more than 6 hours to process?

Gamma Distribution

Kernel and Integration Constant

\[ \begin{aligned} f_Z(z; \alpha, \lambda) &= \frac{\lambda^\alpha}{\Gamma(\alpha)} z^{\alpha-1}e^{-\lambda z} I_{[0,\infty)}(z). \end{aligned} \]

  • PDFs/PMFs must integrate/sum to 1.
  • The functional form can be thought of as two pieces:
    1. The “kernel” is the portion that depends on the argument (\(x\) or \(z\))
    2. The “normalizing constant” is the part that depends only on parameters; this makes the function integrate to 1.
  • The support (given by the indicator function) is part of the kernel.

Kernel and Integration Constant: Example

\[f_Z(z; \alpha, \lambda) = \frac{\lambda^\alpha}{\Gamma(\alpha)} z^{\alpha-1}e^{-\lambda z} I_{[0,\infty)}(z)\]

  1. The kernel is \(z^{\alpha}e^{-\lambda z} I_{[0,\infty)}(z)\).
  2. The normalizing constant is \(\lambda^\alpha / \Gamma(\alpha)\).

We know that \[1 = \int_0^\infty \frac{\lambda^\alpha}{\Gamma(\alpha)} z^{\alpha-1}e^{-\lambda z} \mathsf{d}z \]

which implies

\[ \frac{\Gamma(\alpha)}{\lambda^\alpha} = \int_0^\infty z^{\alpha-1}e^{-\lambda z} \mathsf{d}z.\]

Kernel Matching

\[f_Z(z; \alpha, \lambda) = \frac{\lambda^\alpha}{\Gamma(\alpha)} z^{\alpha-1}e^{-\lambda z} I_{[0,\infty)}(z)\]

  1. What is \[\int_0^\infty z^3 e^{-5z} \mathsf{d}z?\]
  2. What is \[\int_0^\infty z \frac{\lambda^4}{\Gamma(4)} z^{3}e^{-\lambda z} \mathsf{d}z?\]

Hint: Recall that \(\Gamma(n) = (n-1)!\) when \(n \in \{1,2,\dots\}\).

Kernel Matching

Kernel Matching

The Normal (Gaussian) distribution

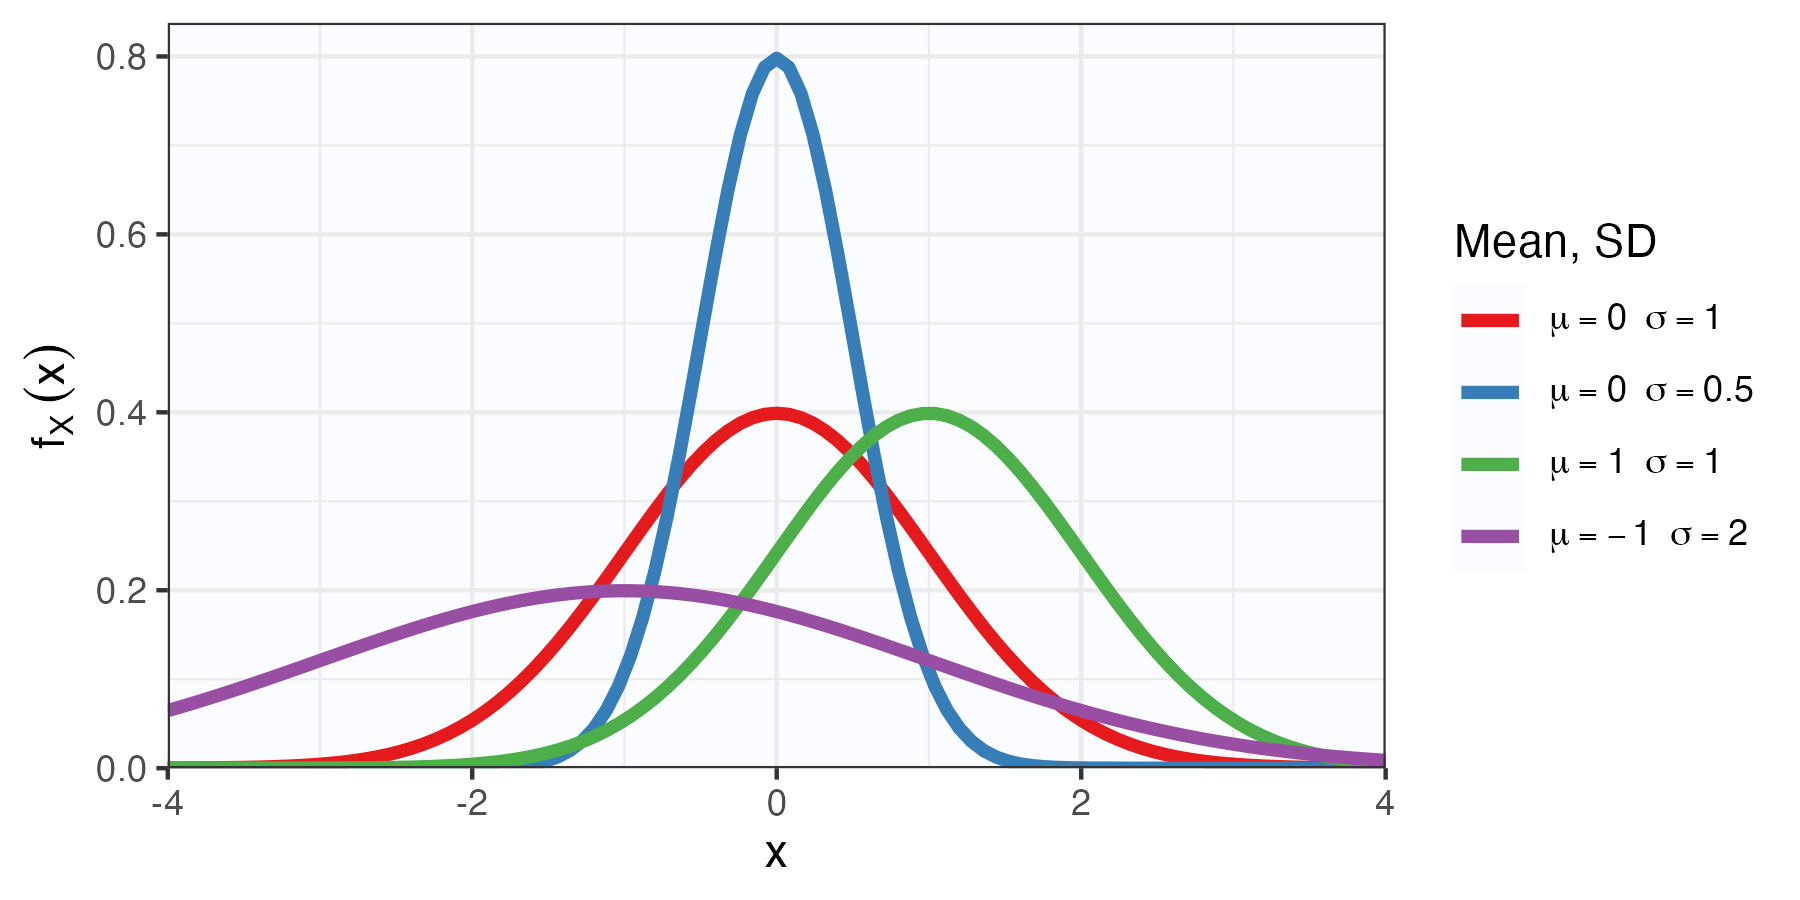
Let \(\mu\in{\mathbb{R}}\), \(\sigma>0\). A RV \(Z\) with pdf \[f_Z(z; \mu, \sigma^2) = \frac{1}{\sqrt{2\pi\sigma^2}} \exp\left\{ -\frac{(z-\mu)^2}{2\sigma^2}\right\},\] is said to have the \(\mathcal{N}(\mu, \sigma^2)\) distribution.
The Normal Distribution

  • This distribution is incredibly important.
  • The reason is that it is good for modelling averages. We’ll justify this rigorously later.
  • \(Z \sim \mathcal{N}(0,1)\) is called the standard normal distribution. When \(Z\) is written without context, it is often understood to have this specific distribution.
  • Unfortunately \[\mathbb{P}(a<Z<b) = \int_a^b \frac{1}{\sqrt{2\pi}} e^{-z^2/ 2} \mathsf{d}z,\] does not have a closed form solution.
  • Can use software or tables in textbooks to calculate this (Table D.2 on p. 712 for you).

Upcoming Assessments:

  • No checkpoints this week - relax after the midterm!

  • Checkpoint 4 (Sections 2.5 - 2.6: Continuous RV and CDFs) is on Friday Oct 30th